All Categories
Featured
Table of Contents
Understanding the EPO Model in San Juan Capistrano
Selecting health coverage for a family in 2026 requires a clear understanding of how different network structures impact both the wallet and the doctor-patient relationship. The Exclusive Provider Organization (EPO) has gained significant traction this year as a middle-ground option. Unlike a Preferred Provider Organization (PPO), an EPO does not pay for any care received outside of the specified network, except in emergency situations. This makes the network list the most important document a consumer reviews during the open enrollment period for Medicare Part D.
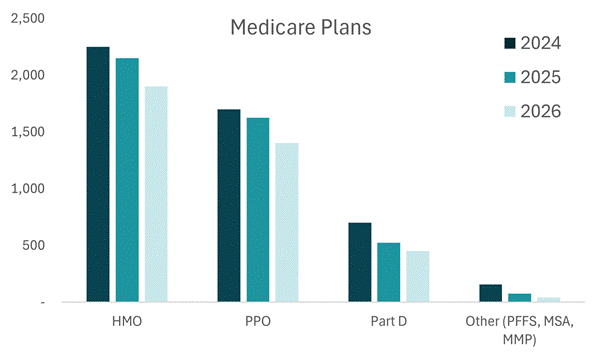
For families living in San Juan Capistrano, the primary appeal of an EPO is the price point. Monthly premiums are typically lower than PPO plans because the insurer has negotiated exclusive rates with a specific group of doctors and hospitals. By limiting where members can go, the insurance company gains more control over costs. For a family with young children or members managing chronic conditions, this trade-off requires a thorough audit of the local provider list before signing up. If a favorite pediatrician or specialist is not on that list, the family must be prepared to switch doctors or pay the full retail price for every visit.
Navigating Provider Networks and Specialty Care
The structure of an EPO is often simpler than a Health Maintenance Organization (HMO) because most EPO plans do not require a referral from a primary care physician to see a specialist. This flexibility is a major selling point for those who want to manage their own care without an extra layer of bureaucracy. However, the "exclusive" nature of the network remains a hard boundary. In 2026, many households are focusing on Harmony SoCal Insurance Services Coverage to ensure that their medical expenses remain predictable throughout the fiscal year.
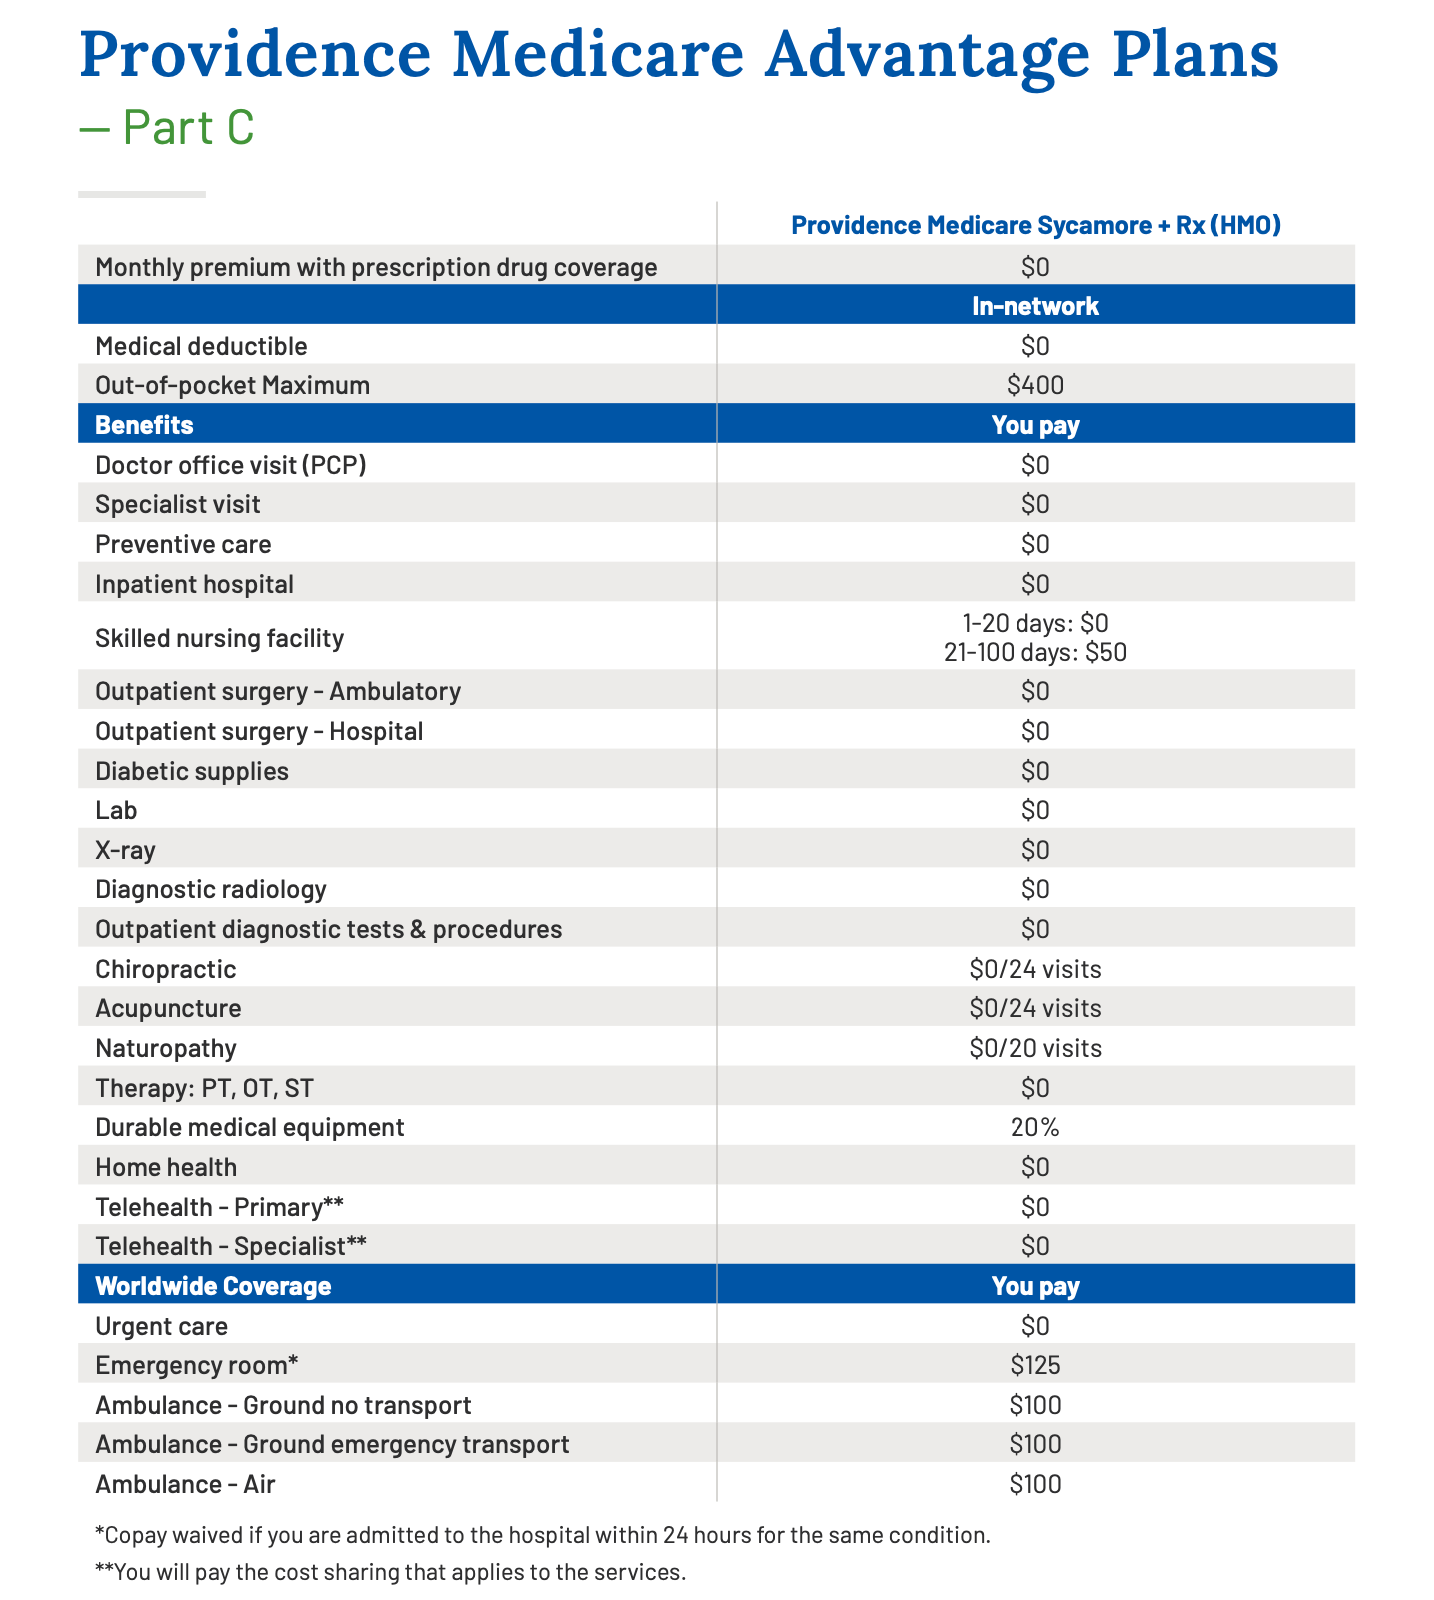
When evaluating an EPO for family use, the size of the network in San Juan Capistrano is more important than the number of plans available. Some insurers have narrowed their networks in 2026 to keep prices stable amid rising medical inflation. A narrow network might include a top-tier hospital system but exclude several independent clinics. Families should verify that the network includes urgent care centers and 24-hour facilities within a reasonable driving distance of their home. If the network is too thin, the lower premium could lead to higher stress when an immediate medical need arises.
Medicare Advantage and EPO Growth in 2026
Medicare beneficiaries in San Juan Capistrano are seeing more EPO options within the Medicare Advantage (Part C) space this year. These plans are designed for seniors who want the lower costs of a managed care plan but dislike the referral requirements of an HMO. Because Medicare Advantage plans often include prescription drug coverage and extra benefits like dental or vision, the EPO model allows the insurer to bundle these services while keeping the monthly plan premium low.

Seniors should be cautious about the geographic limitations of an EPO. While Medicare is a national program, an EPO is inherently local. If a retiree spends half the year in San Juan Capistrano and the other half in a different state, an EPO might not be the best fit unless they only plan to seek routine care in one location. Emergency care is covered anywhere in the United States, but routine check-ups or management of ongoing issues will not be covered outside the local network. Consumers looking into Harmony SoCal Insurance Services Business Insurance find that comparing network maps is just as vital as comparing drug formularies.
Balancing Life Insurance and Health Costs
Health insurance does not exist in a vacuum. Most families in San Juan Capistrano look at their total financial protection, which includes life insurance products. In 2026, the trend of "living benefits" in life insurance has become a standard consideration. These policies allow the holder to access a portion of the death benefit while still alive if they are diagnosed with a chronic or terminal illness. When paired with an EPO health plan, these life insurance products provide a secondary safety net.
If an EPO network does not include a specific high-end specialist for a rare condition, the out-of-pocket costs could be substantial. This is where the cash value or living benefits of a 2026 life insurance policy might be used to bridge the gap. Decisions regarding Medicare Part D should always account for the worst-case scenario. While the EPO saves money on a monthly basis, having a sturdy life insurance policy ensures that the family is protected if a health crisis exceeds the boundaries of the health insurance network.
Direct Advice for 2026 Policy Selection
The best way to approach the 2026 market is to start with a list of "non-negotiable" providers. This includes any specialists, therapists, or hospitals that the family has used in the past year. Once that list is ready, compare it against the EPO directories available in San Juan Capistrano. Many people find that Harmony SoCal Insurance Services in San Juan Capistrano is the most efficient way to narrow down the choices. If the must-have doctors are in the network, the EPO is likely the most cost-effective choice for the year.
Another factor to consider in 2026 is the maximum out-of-pocket limit. Even if the premium is low, a high out-of-pocket maximum can be a risk for families with high medical usage. In 2026, federal regulations have adjusted these limits, and many EPO plans have set their caps slightly lower than PPOs to attract more members. Check the "summary of benefits" document for the specific "family" out-of-pocket limit, rather than just the "individual" limit, to see how the plan handles multiple people hitting their deductibles in the same year.
Final Considerations for Families
The decision to choose an EPO often comes down to a preference for lower fixed costs over the freedom to see any doctor. For a healthy family that stays local and has a primary care doctor they trust within the network, an EPO is a smart financial move. It avoids the referral hurdles of an HMO while keeping the price lower than a PPO. However, for those who travel frequently or have complex medical needs that might require out-of-state specialists, the restrictions of an EPO may prove too tight.
As 2026 continues to see shifts in how Medicare Part D are structured, staying informed about network changes is a year-round task. Insurers sometimes drop providers mid-year, though this is less common than it used to be. Families should keep a close eye on any communications from their insurer regarding network updates. By combining a well-vetted EPO plan with a reliable life insurance policy, households in San Juan Capistrano can build a defensive financial perimeter that protects their health and their assets.

Latest Posts
Why Catastrophic Insurance Is a Safety Net for Young Adults
Choosing Between Indexed and Traditional Universal Life Insurance
Why Life Insurance Is Essential for New Parents in Tustin