All Categories
Featured

Why IUL Insurance Works
Table of Contents
Nationwide also provides you the ability to basically buy additional upside possible with their "High-Cap" or "High-Par" Indexed Universal Life insurance investment techniques, which feature an extra 1%-2% charge. This decreases an IUL's flooring below 0%, there might be years when you want the additional upside potential. Varied Set of IUL Crediting StrategiesUnique Multi-Index StrategyHistory of Treating Inforce Policyholders FairlyLarge Size, Mutuality, and Solid Financial StrengthStrong focus on Volatility Control IndexesGood long-lasting development, but lackluster early cash valuesParticipating policy loan rate is capped to be no greater than 8% Columbus Life Insurance is the IUL arm of the well-rated insurance corporation of Western Southern Group, which went into the IUL arms race in the middle of the last years.
Because their only commitment as a business is to the long-lasting commitment of insurance policy holders, they are most likely to do right by their inforce block of business. This can be plainly seen in this screenshot we just recently sent to one of our clients demonstrating how Columbus Life's IUL cap rates have progressively increased from 8.75% in December 2022 to 10% exactly one year later on as rates ticked up.

The worst IUL companies continuously claim to have the very best Indexed Universal Life insurance coverage policy with the greatest cap. They'll start with an extremely high cap to record market share, then quickly pull the rug out from under their consumers once they shelve that item and start a new one.
That method, insurance policy holders obtaining for outdoors financial investment opportunities still had the potential to earn at least some favorable arbitrage. Strong S&P 500 cap rateParticipating loan rate is topped at 6% (however has been lower for a while)Their documented history of treating in-force insurance policy holders fairlyMutual Holding Business without any outside stockholdersTheir uncapped indexed account is presently unappealing and inactionable.
To clarify, all the very best IUL companies in this post use some sort of free persistent health problem rider, but National Life Group's is arguably the most robust. I also desire to explain that I am particularly discussing their "Peak Life" product, which is their "larger case" product offering a more structured fee structure.
Expert Insurance Advice for Choosing Coverage
Technically the rider is "totally free", but we've discovered when stress-testing costs that the death expenditures are a bit greater than other of the finest IUL business. This is to be anticipated, and you might have heard me say, "There's seldom any offers in insurance. Everything gets priced completely rather quickly."That said, National Life Group is in the running for the very best Indexed Universal Life insurance business for customers looking for a balance of performance, income, and thorough security.
Don't invest too much time on these details as your numbers will certainly differ, however this reveals the type of persistent health problem rider payments they use. to discover which are currently the finest IUL policies with robust Persistent Disease Riders and solid IUL crediting methods for tax-free income if you do not end up being too ill or injured to function independently.
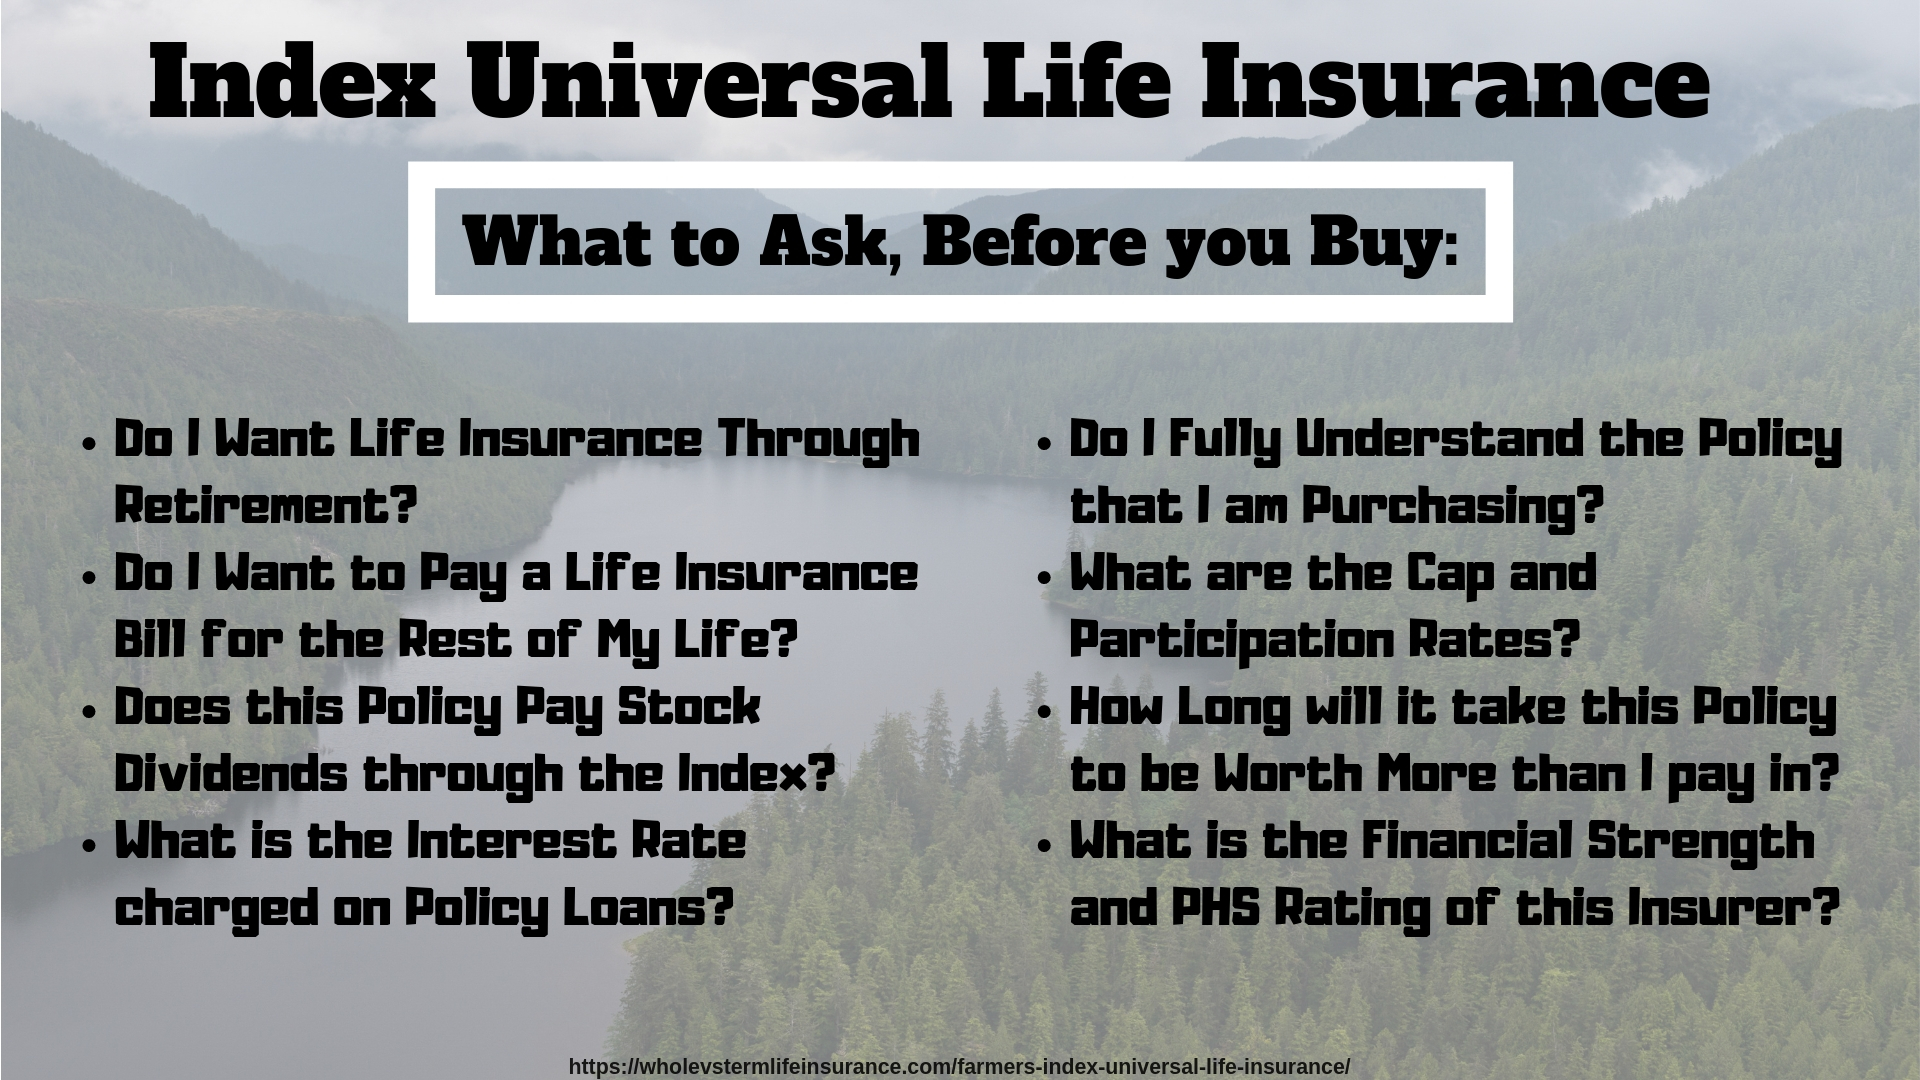
Indexed Universal Life Insurance coverage has numerous moving parts at its core, not to point out all the prospective bells and whistles various business contribute to their policies. Do not just fall for a good story and slick sales pitch. now that you know what to ask. If you're weighing IUL against your existing retirement accounts, our full breakdown of covers the crucial differences in contribution limits, tax treatment, and versatility.
Throughout many of the 1900s the only life insurance coverage products were Whole Life and Term. Term insurance coverage offered lower expenses for short-lived life insurance protection. Whole Life provided an ensured survivor benefit for a guaranteed level premium, but also had a connected cost savings part with an ensured permanent development rate along with non-guaranteed dividends.
Insurance in Hemet CALow-Cost Family Health Insurance
The concept with Universal Life is that the growth of the savings account will decrease the quantity of pure insurance in the policy, which would lower the increasing expense per system of survivor benefit. In 1986, quickly after the meteoric increase of Universal Life, life insurance coverage business had the concept of adding an investment component.
This caused the internal revenue service restricting just how much premium anyone could pump into any quantity of irreversible death benefit for future tax-free retirement earnings. Regardless, as the stock market raged on throughout the 1990s, VUL became the insurance item of option for cash accumulation. In 1997, the very first Indexed Universal Life product was invented by TransAmerica (not on the list of 2026 Best IUL business). At initially, Indexed Universal Life insurance coverage didn't make a big splash at all.

Latest Posts

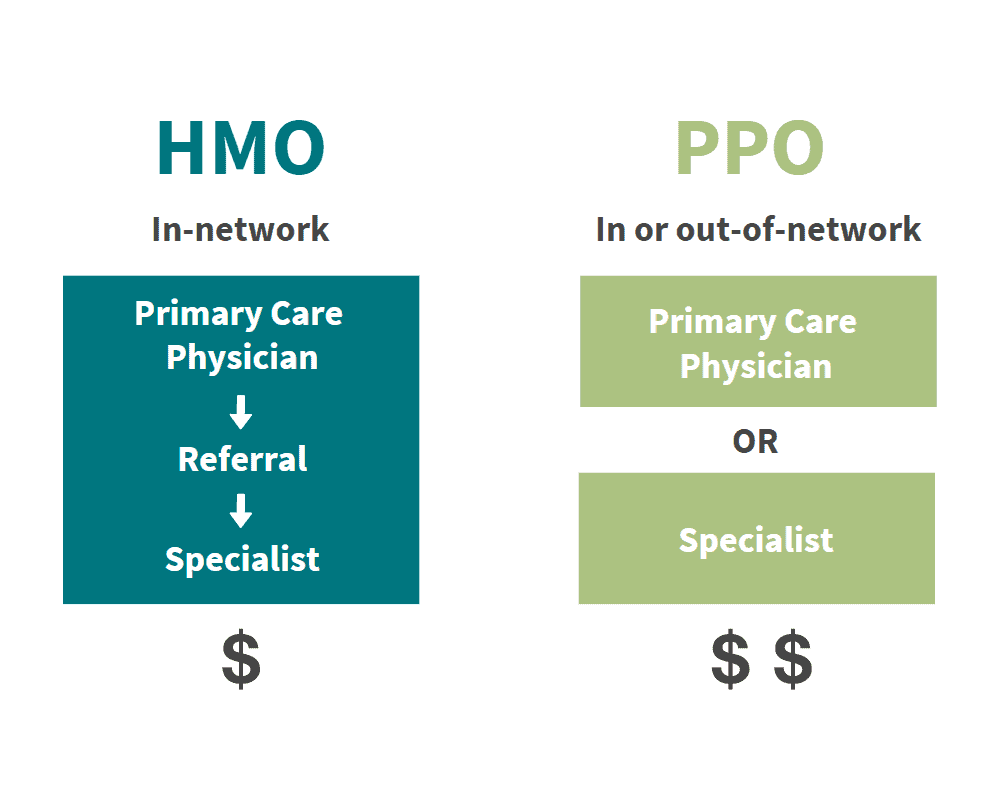
Understanding PPO Versus HMO Plans
Reviewing 2026 Medicare Advantage Options

Understanding Whole and Term Life Insurance Strategies